How the Mortgage Interest Deduction Saves Homeowners Money in 2026
One of the biggest misconceptions about homeownership is that the financial benefits stop once you move in. In reality, owning a home opens the door to significant tax advantages that renters will never experience. If you've been thinking about making the jump from renting to buying in Irving, understanding how these deductions work could save you thousands of dollars every year.
Let me break down one of the most valuable homeowner tax benefits available: the mortgage interest deduction.
What Exactly Is the Mortgage Interest Deduction?
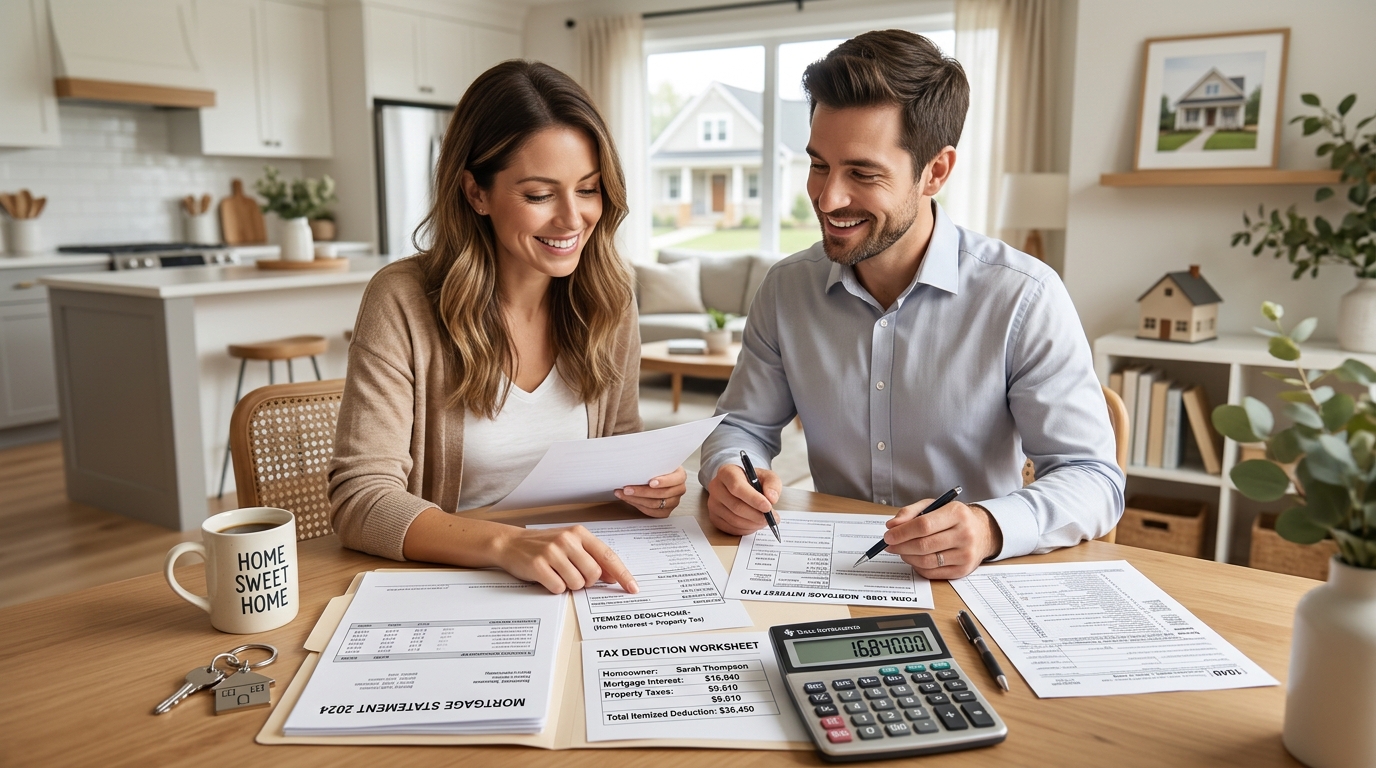
The mortgage interest deduction is a federal tax benefit that allows homeowners to deduct the interest paid on their home loans from their taxable income. When you make a mortgage payment each month, a portion goes toward principal and a portion goes toward interest. That interest portion can be deducted from your taxable income, potentially saving you a substantial amount come tax time.
Here's a practical example to show what this really means. If you paid $15,000 in mortgage interest during the tax year and you're in the 24% tax bracket, this deduction could save you $3,600 in federal taxes. That's nearly a $300 monthly tax savings just by owning your home.
How Much Can You Deduct in 2026?
IRS rules for the 2026 tax year allow eligible homeowners to deduct mortgage interest on up to $750,000 in mortgage debt. If you're married and filing separately, you can deduct interest on up to $375,000. There's one important caveat: these limits apply to mortgages taken out after December 15, 2017. If your mortgage originated before that date, you can deduct interest on up to $1 million.
This $750,000 limit is actually permanent now. For years, homeowners had to plan around a sunset date, wondering if Congress would extend the benefit. That uncertainty is gone. The One Big Beautiful Bill Act locked in these rules for the long term, so you can count on this deduction being available.
Understanding the Itemize vs. Standard Deduction Decision
Here's where many homeowners get confused, so let's clear this up. Claiming the standard deduction makes sense if this deduction is more than the amount you could deduct if you itemize.
In 2026, the standard deduction for married joint filers is $32,200, while the standard deduction for single filers is $16,100. To benefit from the mortgage interest deduction, your total itemized deductions have to exceed these amounts.
Think of it this way: if you're a single filer with $20,000 in mortgage interest but no other deductions, you'd be better off taking the $16,100 standard deduction. But if you combine that $20,000 mortgage interest with property taxes, charitable contributions, or other itemized deductions, you could quickly surpass $16,100 and benefit significantly.
Real Money Savings for Irving Homeowners
Let's look at some actual numbers to see how this works for homebuyers in our Irving area. Say you buy a home at $350,000 with a 7% interest rate:
In year one, you'd pay approximately $24,500 in mortgage interest. If you're in a 24% tax bracket and you itemize your deductions, that $24,500 interest deduction could save you about $5,880 in federal taxes annually. That's real money that stays in your pocket.
Now consider the renter in the apartment next door paying the same amount in rent each month. That renter gets zero tax deductions for their housing costs. They're building equity in their landlord's property while receiving no tax benefits whatsoever.
New Tax Benefits for 2026: PMI Is Back
If you're planning to buy a home in Irving but don't have a 20% down payment, there's excellent news. Beginning with 2026 tax returns, mortgage insurance premiums will again be tax-deductible for qualifying homeowners. This deduction expired after the 2021 tax year, but was reinstated as part of the One Big Beautiful Bill Act and is now permanent.
This is significant for first-time buyers who put down less than 20%. Private mortgage insurance (PMI) can cost hundreds of dollars per month, but now those premiums count as deductible mortgage interest. It's yet another way homeownership becomes financially favorable compared to renting.
Other Homeowner Deductions to Stack With Mortgage Interest
The mortgage interest deduction doesn't exist in a vacuum. When you're deciding whether to itemize, you can combine it with other homeowner deductions.
Property taxes can be claimed as part of the state and local tax deduction, though for the 2026 tax year, the SALT deduction is limited to $40,400. In Texas, we don't have state income tax, but Irving property taxes still count toward this deduction.
Interest on home equity loans and lines of credit may be deductible, but only if you use the money to buy, build, or substantially improve your primary or second home. So if you're planning renovations to increase your home's value, those financing costs could be deductible too.
Why This Matters for Your Irving Home Purchase
The mortgage interest deduction is one reason why buying makes more financial sense than renting long-term. You're not just building equity in a property you'll own outright someday—you're also getting tax deductions that reduce what you owe the government.
When you combine the mortgage interest deduction with the equity you build through monthly payments and potential home appreciation, the financial advantages of homeownership become clear. A renter paying $1,500 per month is essentially writing a check to someone else's wealth building. A homeowner paying a similar amount is building their own.
The Irving real estate market offers excellent opportunities for buyers ready to take advantage of these benefits. If you're currently renting and wondering whether it's the right time to buy, understanding your tax advantages is a crucial part of that decision.
Finding Your Irving Home
Ready to start exploring homeownership opportunities in Irving? As your local real estate agent, I'm here to help you find the right property that fits both your lifestyle and your financial goals. I can also connect you with a tax professional who can run specific numbers based on your situation.
Use HOUSEJET to start browsing available homes in Irving, or reach out to me directly to discuss how the mortgage interest deduction might specifically benefit your financial situation. The sooner you understand these tax advantages, the sooner you can start building equity and enjoying the benefits of homeownership.
Your path to homeownership starts with knowledge, and understanding the mortgage interest deduction is an important piece of that puzzle.